Lenskart Q3 FY26 profit jump explained, plus Q4 and Q1 FY27 results
Lenskart's Q3 FY26 profit rose to ₹132.7 crore, a '70x' jump that is 3.4x like-for-like. What Q4 FY26 and the latest Q1 FY27 filings now show.
 Ishaan Vardhan24 Oct 2026 · 8 min read
Lenskart’s profit for October to December 2025 (Q3 FY26), its first full quarter as a listed company, was ₹132.7 crore, up from ₹1.85 crore a year earlier on reported numbers, according to Entrackr. That is the “70x” headline. On the like-for-like basis the company itself uses, profit rose 3.4 times, while revenue grew about 38% to ₹2,308 crore.
Lenskart has reported two more quarters since. In the latest, April to June 2026 (Q1 FY27), revenue rose 33.6% to ₹2,714 crore and profit reached ₹228 crore, up from ₹81 crore, according to its 12 August 2026 shareholders’ letter. This article explains all three results and what is driving them.
Key takeaways
- Q3 FY26 revenue rose 38.3% to ₹2,307.7 crore, and EBITDA margin widened to 20.0% from 14.5%, according to Upstox.
- The “70x” profit jump compares against a reported year-ago figure distorted by acquisitions; Lenskart’s pro forma comparison shows 3.4x growth.
- FY26 (the year to March 2026) closed with ₹9,002 crore of revenue and ₹530 crore of adjusted profit, 2.5 times the previous year.
- Q1 FY27 profit of ₹228 crore was close to half of the whole of FY26, and consolidated product margin crossed 70% for the first time.
- International markets, led by Japan, Singapore, Thailand and the Middle East, made up about 40% of Q3 FY26 revenue and about 44% in Q1 FY27.
Lenskart in brief
Lenskart Solutions was established in 2008 and designs, makes and sells prescription glasses, sunglasses and contact lenses, mainly in India but with a presence in 14 countries, according to Business Standard. Its promoters are Peyush Bansal, Neha Bansal, Amit Chaudhary and Sumeet Kapahi. It owns the Japanese eyewear chain Owndays and the Barcelona-founded sunglasses brand Meller.
The company listed on the NSE and BSE on 10 November 2025 after a ₹7,278 crore IPO priced at ₹402 a share, made up of a ₹2,150 crore fresh issue and a ₹5,128 crore offer for sale, according to Chittorgarh. The IPO was subscribed 28.26 times, but the shares listed at ₹390 on the BSE, a 3% discount, Business Standard reported.
A note on terms: Indian companies report in crore (1 crore = 10 million rupees) and lakh (1 lakh = 100,000). The Indian financial year runs April to March.
Q3 FY26: what the numbers say
Lenskart announced its Q3 FY26 results on 11 February 2026. On reported numbers, as compiled by Upstox and Entrackr:
| Metric | Q3 FY26 | Q3 FY25 | Change |
|---|---|---|---|
| Revenue from operations | ₹2,307.7 crore | ₹1,668.8 crore | +38.3% |
| EBITDA | ₹462.4 crore | n/a | +90.6% |
| EBITDA margin | 20.0% | 14.5% | +5.5 points |
| Profit after tax | ₹132.7 crore | ₹1.85 crore | about 71x |
India contributed ₹1,385 crore of revenue and international markets ₹936 crore, or about 40%, Entrackr reported. Employee costs rose 62.5% to ₹528 crore, reflecting the pace of store openings.
Why “70x” overstates it
Lenskart’s own Q3 shareholders’ letter uses pro forma figures. These restate the year-ago period as if Lenskart had already consolidated its master franchisee Dealskart, the location-analytics firm GeoIQ and Meller. On that basis, Q3 FY25 profit was ₹39.3 crore, so Q3 FY26 profit was 3.4 times higher, not 70 times. The letter says reported and pro forma figures are identical from Q3 FY26 onward, so the gap only affects comparisons with earlier periods.
Even the pro forma growth is large, and the letter attributes it to operating leverage rather than cost cuts. EBITDA grew more than twice as fast as revenue. Q3 profit was also reduced by ₹5.3 crore of one-off IPO expenses booked as exceptional items.
What drove the quarter
The letter points to volume, not price. Eyewear units rose 29.7%. Lenskart ran 6.3 million eye tests in the quarter, up 54%, and said 49% of the 5.5 million tests in India were people’s first eye exam. India same-store sales grew 27.8%. The company added 195 net new stores, and its Gold membership programme reached 8.1 million active members.
Q4 FY26 and the full year
Lenskart reported its January to March 2026 results on 20 May. Reported revenue rose 45.6% to ₹2,515.7 crore, and EBITDA margin widened to 21.3% from 18.6%, according to Upstox.
Reported profit fell 8.5% to ₹200.3 crore from ₹218.9 crore, which looks odd next to that growth. The explanation is in the company’s Q4 shareholders’ letter. FY25 profit included a one-time, non-cash gain of ₹167.2 crore on deferred consideration for the Owndays acquisition. Stripping that out, Lenskart says adjusted profit grew 2.6 times to ₹203.6 crore in Q4.
For the full year FY26, the letter reports:
- Revenue of ₹9,002.3 crore, up 32.3%.
- EBITDA of ₹1,789.5 crore, up 55.3%, with margin rising to 19.9% from 16.9%.
- Adjusted profit of ₹530 crore, 2.5 times FY25.
- 603 net new stores (542 in India, 61 abroad), taking the total to 3,327.
Q1 FY27: the latest reported quarter
The April to June 2026 quarter, reported on 12 August, continued the trend. According to the Q1 FY27 shareholders’ letter and Outlook Business:
| Metric | Q1 FY27 | Q1 FY26 | Change |
|---|---|---|---|
| Revenue from operations | ₹2,714 crore | ₹1,894 crore (reported) | +33.6% (pro forma) |
| EBITDA | ₹589 crore | n/a | +61.3% |
| EBITDA margin | 21.7% | 18.0% | +3.7 points |
| Profit after tax | ₹228 crore | ₹81 crore | 2.8x |
| Product margin | 70.3% | 68.7% | +1.6 points |
Outlook Business compared Q1 FY27 revenue with the reported ₹1,894 crore a year earlier, while the 33.6% growth figure is on Lenskart’s pro forma basis. Profit is the clearer measure here: ₹228 crore in one quarter, against about ₹530 crore for the whole of FY26.
Other details from the letter:
- India revenue grew 30.7% to ₹1,531 crore, with same-store sales growth slowing to 18.3%.
- International revenue grew 38% to ₹1,203 crore, helped by favourable currency movements.
- 132 net new stores took the total to 3,459. Gold members reached 93.5 lakh (9.35 million).
- Operating cash flow of ₹297 crore covered ₹207 crore of capital spending, much of it on a new manufacturing plant in Hyderabad.
- Net cash, excluding IPO-related payables, stood at ₹4,104 crore.
The international business
Lenskart’s overseas business is no longer a side project. In its Q3 letter, the company said it had 705 international stores and the number one position in Singapore, where it runs both Owndays and Lenskart stores. It described Japan, where Owndays is based, as its largest international market, and said it had 23 stores in the UAE and 18 in Saudi Arabia.
The company argues its overseas stores are more profitable than India was at a similar size. International product margin was 77.1% in Q1 FY27, against 64.2% in India, according to the Q1 letter, because selling prices abroad are far higher. Meller, which the letter says was a $35 million brand when acquired, is now tracking towards about $70 million in annual sales. The board also approved a larger stake in Baofeng Framekart, its frame-making joint venture in China, and new step-down subsidiaries in South Korea and China, Outlook Business reported.
The risks in the numbers
Three issues stand out from the company’s own disclosures.
- Currency. A meaningful share of Lenskart’s frames is sourced from China, so a weaker rupee against the renminbi raises costs. The Q1 FY27 letter says premium products and in-house manufacturing absorbed the impact so far, and the new Hyderabad plant is meant to reduce this exposure.
- Slowing same-store growth. India same-store sales growth eased from 27.8% in Q3 FY26 to 18.3% in Q1 FY27. That is still strong, but growth is leaning more on new stores.
- Valuation. Lenskart shares closed at ₹691.15 on the NSE on 1 October 2026, about 72% above the IPO price, after touching ₹725 on 18 September, according to Chittorgarh. At that level, investors are paying for many years of growth at the current pace.
Bottom line
The old version of this story called Q3 FY26 a “profit surge”. That was true but incomplete. Much of the 70x headline came from comparing against a year-ago figure that did not include acquisitions, and Lenskart’s own like-for-like number was 3.4x. What has held up over the following two quarters is the underlying pattern: revenue growing 30% to 40%, profit growing much faster, and stores and eye tests expanding together.
For founders building consumer brands, Lenskart is a useful example of how owning manufacturing, data and distribution can turn growth into margin once a business reaches scale. For more company results and startup news, see our news section, and for recent private rounds in consumer and retail, our funding tracker. We will update this article when Lenskart reports its July to September 2026 quarter.
This article reports company results and is not investment advice. Check the filings and consult a registered financial adviser before making investment decisions.
FAQ
What was Lenskart’s Q3 FY26 profit?
₹132.7 crore for October to December 2025, against ₹1.85 crore a year earlier on reported numbers, or ₹39.3 crore on Lenskart’s pro forma basis.
Why did Lenskart’s profit rise 70 times?
The reported year-ago figure was low and did not include later acquisitions. On a like-for-like pro forma basis, profit rose 3.4 times.
What were Lenskart’s latest quarterly results?
For Q1 FY27 (April to June 2026), revenue was ₹2,714 crore, up 33.6%, and profit was ₹228 crore, up from ₹81 crore.
What was Lenskart’s FY26 revenue and profit?
Revenue of ₹9,002.3 crore and adjusted profit of ₹530 crore, according to the company’s Q4 shareholders’ letter.
Why did Lenskart’s Q4 FY26 reported profit fall?
The year-ago period included a one-time, non-cash gain linked to the Owndays acquisition. Excluding it, adjusted Q4 profit grew 2.6 times.
How many stores does Lenskart have?
3,459 active stores at the end of June 2026, after adding 132 in Q1 FY27.
Sources
- Entrackr, “Lenskart profit jumps to Rs 133 Cr in Q3 FY26; global biz forms 40% of revenue”, 11 February 2026
- Upstox, “Lenskart Solutions Q3 results: Net profit skyrockets nearly 70x YoY”, 11 February 2026
- Lenskart Solutions, “Shareholders’ Letter and Results, Q3 FY26”, 11 February 2026
- Lenskart Solutions, “Shareholders’ Letter, Q4 FY26”, 20 May 2026
- Upstox, “Lenskart Q4 results: key details”, 20 May 2026
- Lenskart Solutions (NSE filing), “Shareholders’ Letter, Q1 FY27”, 12 August 2026
- Outlook Business, “Lenskart Q1 Profit Jumps 182% YoY To ₹228 Crore; Product Margin Crosses 70%”, 12 August 2026
- Business Standard, “Lenskart Solutions makes muted debut despite robust IPO demand”, 10 November 2025
- Chittorgarh, “Lenskart Solutions IPO”, accessed 4 October 2026
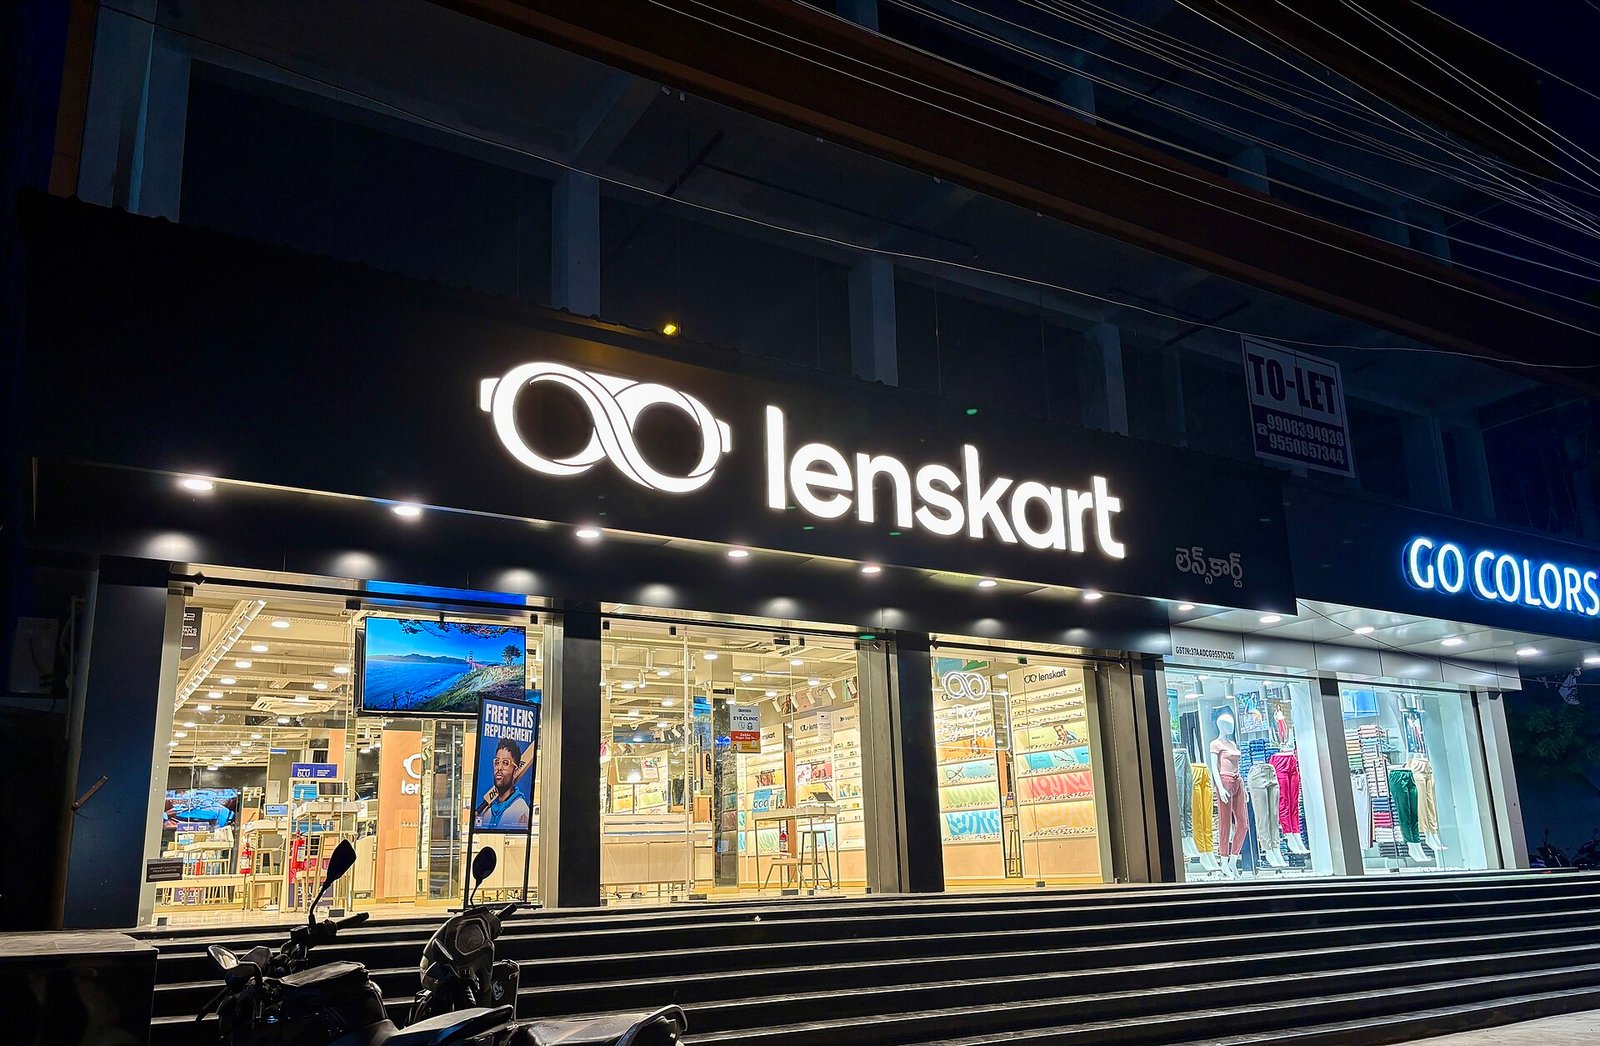
Featured image: A Lenskart store in Ashok Nagar. The company had 3,459 active stores at the end of June 2026. · Photo: Saishna96 / Wikimedia Commons, CC BY-SA 4.0
How this article was made: researched and drafted with AI assistance by the 100xFounder editorial desk, using only the sources listed in it; every figure links to its source. Read our editorial policy, or report an error through our corrections policy.
Related stories
Sources (9)
- Entrackr 11 Feb 2026Q3 FY26 revenue Rs 2,308 Cr vs 1,669 Cr; PAT Rs 132.7 Cr vs Rs 1.85 Cr; India Rs 1,385 Cr, international Rs 936 Cr (40%); employee costs Rs 528 Cr (+62.5%)
- Upstox 11 Feb 2026Revenue Rs 2,307.73 Cr vs Rs 1,668.84 Cr (+38.28%); EBITDA Rs 462.4 Cr (+90.6%), margin 20.0% vs 14.5%
- Lenskart Solutions 11 Feb 2026Pro forma PAT Rs 1,327 Mn vs Rs 393 Mn (3.4x); revenue +37.4%; India +40.4%, international +32.7%; 6.3M eye tests; SSSG 27.8%; 195 net new stores; 8.1M Gold; Rs 53 Mn IPO exceptional; 705 intl stores; Singapore #1; UAE 23 stores, Saudi 18
- Lenskart Solutions 20 May 2026FY26 revenue Rs 90,023 Mn (+32.3%), EBITDA Rs 17,895 Mn (+55.3%), adj PAT Rs 5,300 Mn; Q4 adj PAT Rs 2,036 Mn vs Rs 770 Mn; FVTPL gain Rs 1,672 Mn excluded; 603 net new stores, 3,327 total
- Upstox 20 May 2026Q4 FY26 reported PAT Rs 200.28 Cr vs Rs 218.88 Cr (-8.49%); revenue Rs 2,515.7 Cr vs Rs 1,727.57 Cr (+45.62%); EBITDA margin 21.3% vs 18.6%
- Lenskart Solutions (NSE filing) 12 Aug 2026Q1 FY27 revenue +33.6%, PAT Rs 228 Cr vs Rs 81 Cr; product margin 70.3%; India Rs 1,531 Cr (+30.7%), international Rs 1,203 Cr (+38%); SSSG 18.3%; 3,459 stores; Gold 93.5 lakh; OCF Rs 297 Cr, capex Rs 207 Cr; net cash Rs 4,104 Cr; RMB currency pressure; Meller $35M to ~$70M
- Outlook Business 12 Aug 2026Q1 FY27 revenue Rs 2,714 Cr vs Rs 1,894 Cr; EBITDA Rs 589 Cr (+61.3%), margin 21.7% vs 18%; board approvals Baofeng Framekart stake, South Korea and China subsidiaries
- Business Standard 10 Nov 2025Listed at Rs 390 on BSE vs Rs 402 issue price; 28.26x subscribed; promoters; established 2008; 14 countries
- Chittorgarh 4 Oct 2026IPO Rs 7,278 Cr (fresh Rs 2,150 Cr, OFS Rs 5,128 Cr) at Rs 402, listed 10 Nov 2025; NSE close Rs 691.15 on 1 Oct 2026; 52-week high Rs 725 on 18 Sep 2026